Property insurance · Based in Macclesfield, serving the North West and beyond
Property and landlord insurance across the North West and beyond
Whether you let a single flat, own the building your business trades from or manage a mixed portfolio, we'll find cover that protects your investment.
- Landlord and let property
- Shops, offices and industrial units
- Single properties or portfolios
Speak to Steve and the team
01625 682 765Get a quick quote
Four quick details and we'll call you back promptly during office hours, or on the next working day.
What is property insurance?
Property insurance protects the building itself and the income it produces. For a landlord that means the structure, anything you have furnished it with, and the rent you would lose if a tenant had to move out. For an owner-occupier it means the premises your business depends on, and the cost of trading somewhere else while repairs are done.
Let property is a specialist area. A standard home insurance policy is written for owner-occupiers and normally will not respond once a property is tenanted, and it will not include the property owners' liability cover that letting brings with it. HMOs, student lets, holiday lets and properties let to housing associations each come with their own underwriting questions.
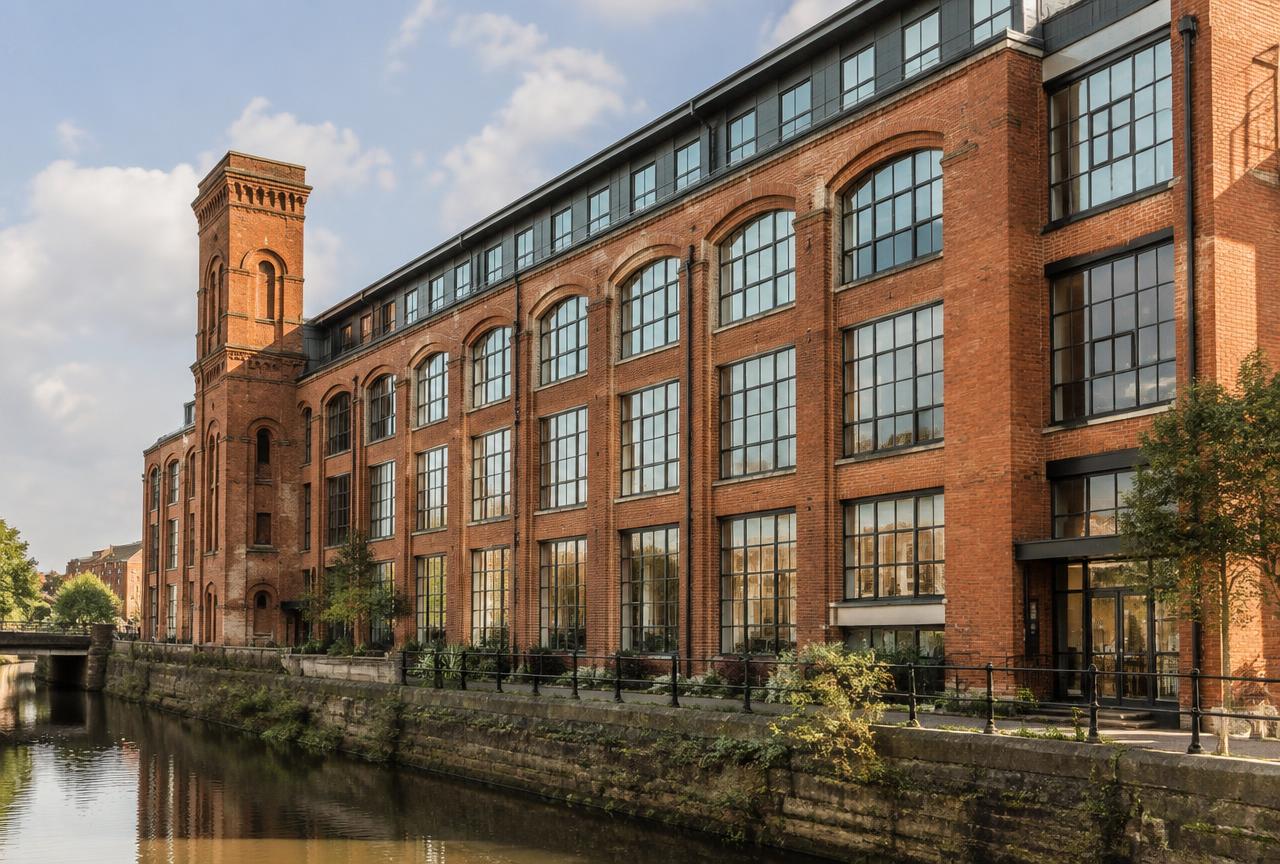
Around Macclesfield and Bollington we see a lot of older stock: Victorian terraces, converted mill space, flats above shops. Age, construction and how a building is used all affect what insurers will offer, so it pays to describe the property accurately from the start. We will tell you what matters and what does not.
Reviewed by Steve Milner, Cert CII · October 2026
A starting point for your cover
Which property insurance cover do I need?
Question 1 of 3
This is a quick guide, not advice. We'll confirm the right cover when we speak to you.
Who we insure
The businesses we work with
Residential landlords
Buildings, landlord contents, loss of rent and property owners' liability for single lets.
HMO landlords
Specialist cover reflecting tenant numbers, licensing and shared facilities.
Portfolio landlords
Several properties on one schedule, with one renewal date.
Commercial property owners
Cover for shops, offices and units you let out, including loss of rent.
Mixed-use (flats over shops)
One policy for buildings with both commercial and residential parts.
Developers and refurbishments
Cover for empty properties and buildings under renovation, until they're ready to let or sell.
- Owner-occupiers
- Property developers
- Blocks of flats and residents' associations
- Holiday lets
Your cover
What can property insurance cover?
Every policy is built around your business, so yours may include some of these and not others.
Core cover
Buildings
The structure, fixtures and fittings, usually on a rebuild-cost basis rather than market value, including outbuildings and boundary walls where needed.
Landlord contents
Carpets, white goods, furniture and anything else you have provided in a furnished or part-furnished let.
Loss of rent and alternative accommodation
Covers rent you lose and the cost of rehousing tenants while an insured event is put right.
Property owners' liability
Protects you if a tenant, visitor or passer-by is injured, or their property is damaged, because of the building you own.
Unoccupied property
Specialist cover for periods between tenancies or during refurbishment, when standard policies restrict what they will pay for.
Legal expenses and rent guarantee
Support with possession proceedings and tenant disputes, and cover for rent arrears where it is available.
HMO cover
Specialist cover for houses in multiple occupation, reflecting tenant numbers, licensing and shared facilities.
Commercial property
Buildings, property owners’ liability and loss of rent options for shops, offices and units, including mixed-use buildings.
Optional extras
- Accidental damage
- Malicious damage by tenants
- Rent guarantee
- Employers' liability if you employ cleaners or maintenance staff
- Trace and access
- Terrorism
Not usually covered
- Tenants' own belongings
- Wear and tear, damp and gradual damage
- An empty property beyond the policy's unoccupancy period, often 30 to 90 days, unless declared
Cover is subject to the insurer's acceptance and policy terms.
How cover can help
Illustrative examples. Whether a claim is covered depends on your policy terms and the insurer's assessment.
Illustrative example
A leak affects two units
A leak from a flat above a shop damages both units.
Buildings cover and loss of rent can respond.
Illustrative example
A tenant is injured
A tenant trips on a loose stair rail.
Property owners' liability can respond to an injury claim.
Illustrative example
Empty between lets
A house is empty for two months between lets.
Declaring it keeps cover in place under unoccupied conditions, subject to insurer acceptance.
How much does property insurance cost?
Every quote is individual, so we don't publish prices. These are the main things insurers look at.
What affects the price
- Rebuild cost
- Location and postcode
- Construction and age
- Tenant type
- Occupancy
- Claims history
- Security
- Excess
Ways to keep your premium down
- An accurate rebuild valuation
- Keeping maintenance records
- Good security
- Combining properties on one portfolio policy
- A higher excess
What you'll need for a property quote
- Property address and postcode
- Rebuild cost estimate
- Construction and age
- Tenant type and tenancy
- Occupancy status
- Claims history
- Mortgage lender details
Don't have everything? We can help fill in the gaps.
Call us now, or request a callback and we'll call you back promptly.
01625 682 765How it works
Getting insured with M&B is SO simple
- 1
Tell us about your business
Fill in a short form or give us a call. We only ask for what we actually need to get started.
- 2
We do the legwork
We approach insurers on our panel and compare cover, not just price. We'll call you back promptly, or on the next working day.
- 3
You choose, we sort the rest
We explain your options in plain English, arrange your policy and stay with you for renewals and claims.
Why M&B
Why choose M&B for property insurance
We know the local housing stock
Mill conversions, stone cottages and flats over shops raise questions insurers care about, and we know how to answer them.
Portfolios kept tidy
We can bring several properties onto one schedule with a single renewal date, which makes adding a purchase much simpler.
Straight answers on rebuild values
Underinsurance is the biggest problem we see with property cover. We will flag it rather than quietly quote a low premium.
Your broker
Steve Milner
Co-Founder & Director · Cert CII
Steve has over 20 years' experience in insurance, leading teams and departments at regional, national and global brokers. He's Cert CII qualified, started his career in Bollington and lives in Macclesfield with his family.
Steve leads a small team based together in our Macclesfield office, each with over 10 years' insurance experience.
“I want to build a broker that puts the customer at the heart of everything we do, with the personal touch and genuine service I feel is missing in the industry today.”
- Macclesfield local
- Over 20 years in insurance
- Cert CII qualified
FAQs
Property insurance questions
Get your property quote
Request a quote
Tell us a little about your business and we'll get to work.
Prefer to talk?
Call 01625 682 765, Monday to Friday, 9:00am – 5:00pm.
Related cover
Commercial insurance
Protect your business assets, premises and company vehicles against everyday trading liabilities and financial losses.
Get a quoteStill not sure which cover you need? Read our insurance FAQs or talk to the team.
Ready to make your insurance SO simple?
Speak to Steve and the team on 01625 682 765, or request a callback and we'll contact you promptly.